We're sorry! This page has moved. We're redirecting you now—if it doesn’t happen automatically, please click the link below:


To our Investors and Partners,
Canada's office fundamentals improved again in Q3, even as the expected outlook for interest rates shifted higher. In September, we hosted a salon dinner in Ottawa with Adam Champy, Chief Product Officer at VTS, the leasing and asset-management platform we use across our portfolio.
The conversation with Adam ranged from cybersecurity to philosophy, the latter courtesy of an investor who had clearly been reading his Aristotle! Rather than debate whether AI will erode office demand, Adam suggested AI is complementary and space needs should be planned on that basis. Ultimately all roads led to Rome: well-located, well-run buildings that bring people together remain the first choice. People still want to work through hard problems together and in person. At Crown we believe that to be a core truth, and it shapes how we invest and operate our buildings.
Market Backdrop
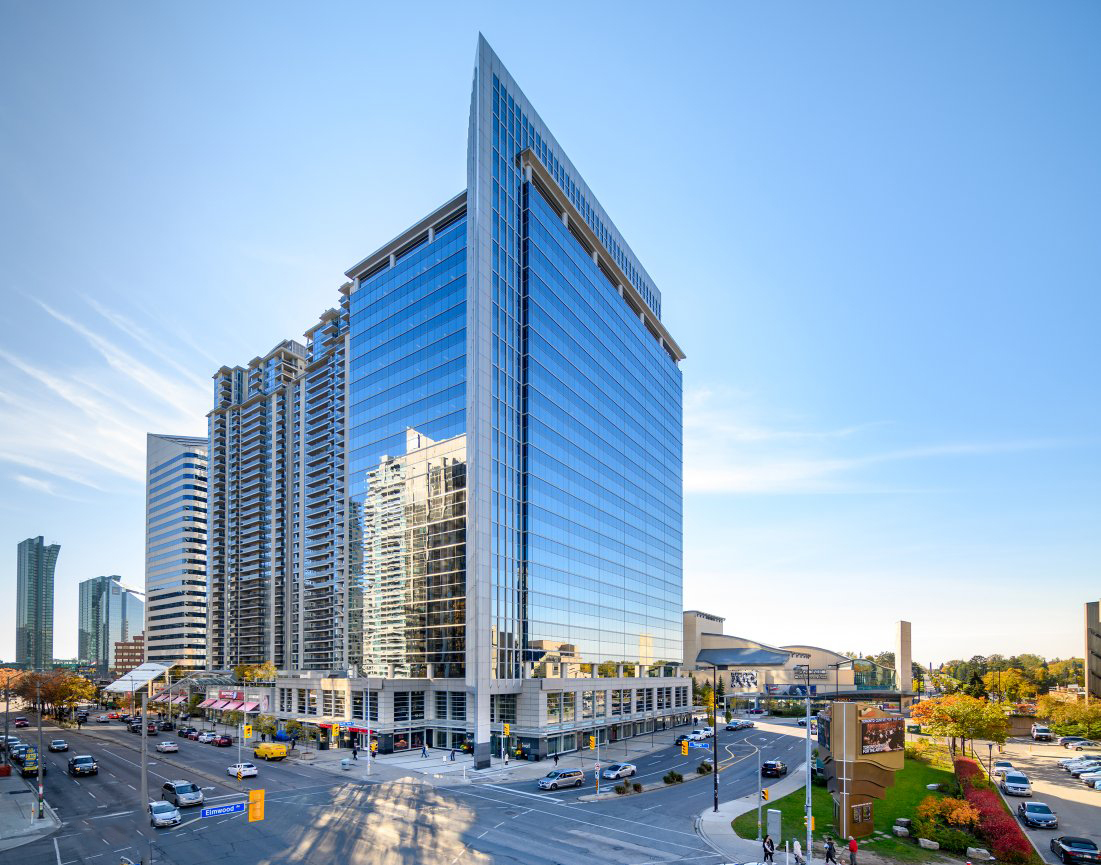
The Bank of Canada has hiked rates by 25 bps in October, with major banks forecasting increases through 2027 to combat energy-driven inflation. With the cost of capital unlikely to fall, returns must come from what we control: what we pay, how we lease and how we run our buildings. That is how we underwrote our recent value-add office acquisition in downtown Toronto, where we expect NOI to more than quadruple over five years.
Office Fundamentals
According to CBRE, Canadian downtown vacancy fell for a fifth consecutive quarter, led by Toronto (down 90 basis points) and Ottawa (down 80). National net absorption was 2.0 million sq. ft., and sublease space has fallen to about half its peak. The recovery remains uneven. Trophy vacancy is at a six-year low nationally and at or below 3% in Toronto, while the gap between top-tier and older buildings is the widest on record. With new supply effectively fixed until 2032, demand for better space can only be met by upgrading existing stock. Repositioning those buildings is precisely what Crown has been doing for the past 25 years.
Crown Highlights of the Quarter
We measure ourselves by results. Year to date, fund NOI increased 7.8% on a same-asset basis, and we completed 577,670 sq. ft. of leasing, putting us at 74% of our annual budget, with 83% of leases renewed or replaced at or above in-place rents.
Looking Ahead
Across private markets, high valuations and a higher cost of debt leave less room for leverage and cap-rate compression to drive returns. More of the return has to come from running assets well. In office, prices have largely reset, and there is still plenty to gain from better leasing and management. CR VI LP, our next value-add fund, is built on that premise. It is also how we have always created value: lease by lease, building by building.
Our priorities for the rest of 2026 are unchanged: return capital to investors, keep leasing ahead of budget, complete the first closing of our newest value add Fund VI, and buy only where we see a credible path to higher income.
Which brings us back to Aristotle, who observed that we deliberate only about "things that are in our power and can be done." Interest rates, capital flows and the pace of AI adoption are exogenous. What we pay, how we run our buildings and how well we serve our tenants are not, and that is where we keep our attention.
Thank you for your continued partnership. Should you be interested, I would be glad to talk through our outlook, our pipeline or CR VI LP.